China’s largest electric vehicle manufacturers are making a calculated bet that the next growth frontier lies not on the road but on two legs. Companies including BYD, Xpeng, and Chery are accelerating investment in humanoid robotics, redirecting engineering talent and capital as a prolonged price war and softening consumer demand erode profitability across the domestic car market. The strategic pivot, reported by CNBC’s analysis, signals a broader structural shift in how China’s automotive champions view their long-term industrial identity.
The timing is not coincidental. China’s passenger vehicle market, which had been propelled by aggressive EV adoption subsidies and surging export volumes, has entered a period of marked deceleration. Average selling prices across major EV segments have fallen by an estimated 15 to 20 percent over the past two years as manufacturers fought for market share, compressing operating margins industry-wide. That dynamic has forced boardrooms to look beyond cars for sustainable revenue streams — and humanoid robots, which carry potentially far higher margins once scaled, have emerged as the consensus answer. The trend also intersects with broader concerns about Chinese domestic demand, which has remained stubbornly fragile across multiple consumer categories.
Manufacturing Expertise Finds a New Application
The logic underpinning the pivot is grounded in genuine industrial overlap. EV production requires mastery of battery systems, electric motors, sensor integration, and sophisticated software stacks — capabilities that map directly onto the engineering requirements of bipedal robots. Xpeng’s robotics division, operating under the AGIBOT brand partnership model, has publicly targeted annual production capacity of 10,000 humanoid units by the end of 2026, a figure that underscores the seriousness with which the company is treating the opportunity rather than treating it as a public relations exercise.
BYD, the world’s largest EV producer by volume, has similarly confirmed internal development programs focused on humanoid platforms intended initially for use within its own manufacturing plants. Industry analysts estimate that deploying humanoid robots in automotive assembly could reduce per-unit labour costs by up to 30 percent at scale, giving vertically integrated EV makers a secondary efficiency dividend on top of any commercial sales revenue. The dual-use rationale — robots that work in your own factories while also being sold externally — makes the economics unusually compelling compared with a standalone robotics venture.
Capital Flows and Competitive Pressure from Beijing
State backing is amplifying private-sector momentum. Beijing has identified humanoid robotics as a strategic technology category under its latest industrial policy framework, earmarking substantial funding through provincial governments and state-linked venture vehicles. Several Chinese municipalities have established dedicated humanoid robot industrial parks, with Shenzhen and Shanghai each committing multi-billion yuan incentive packages to attract anchor tenants. The policy environment mirrors the support structure that catalysed China’s EV dominance a decade ago, raising the prospect of a similarly rapid scaling trajectory.
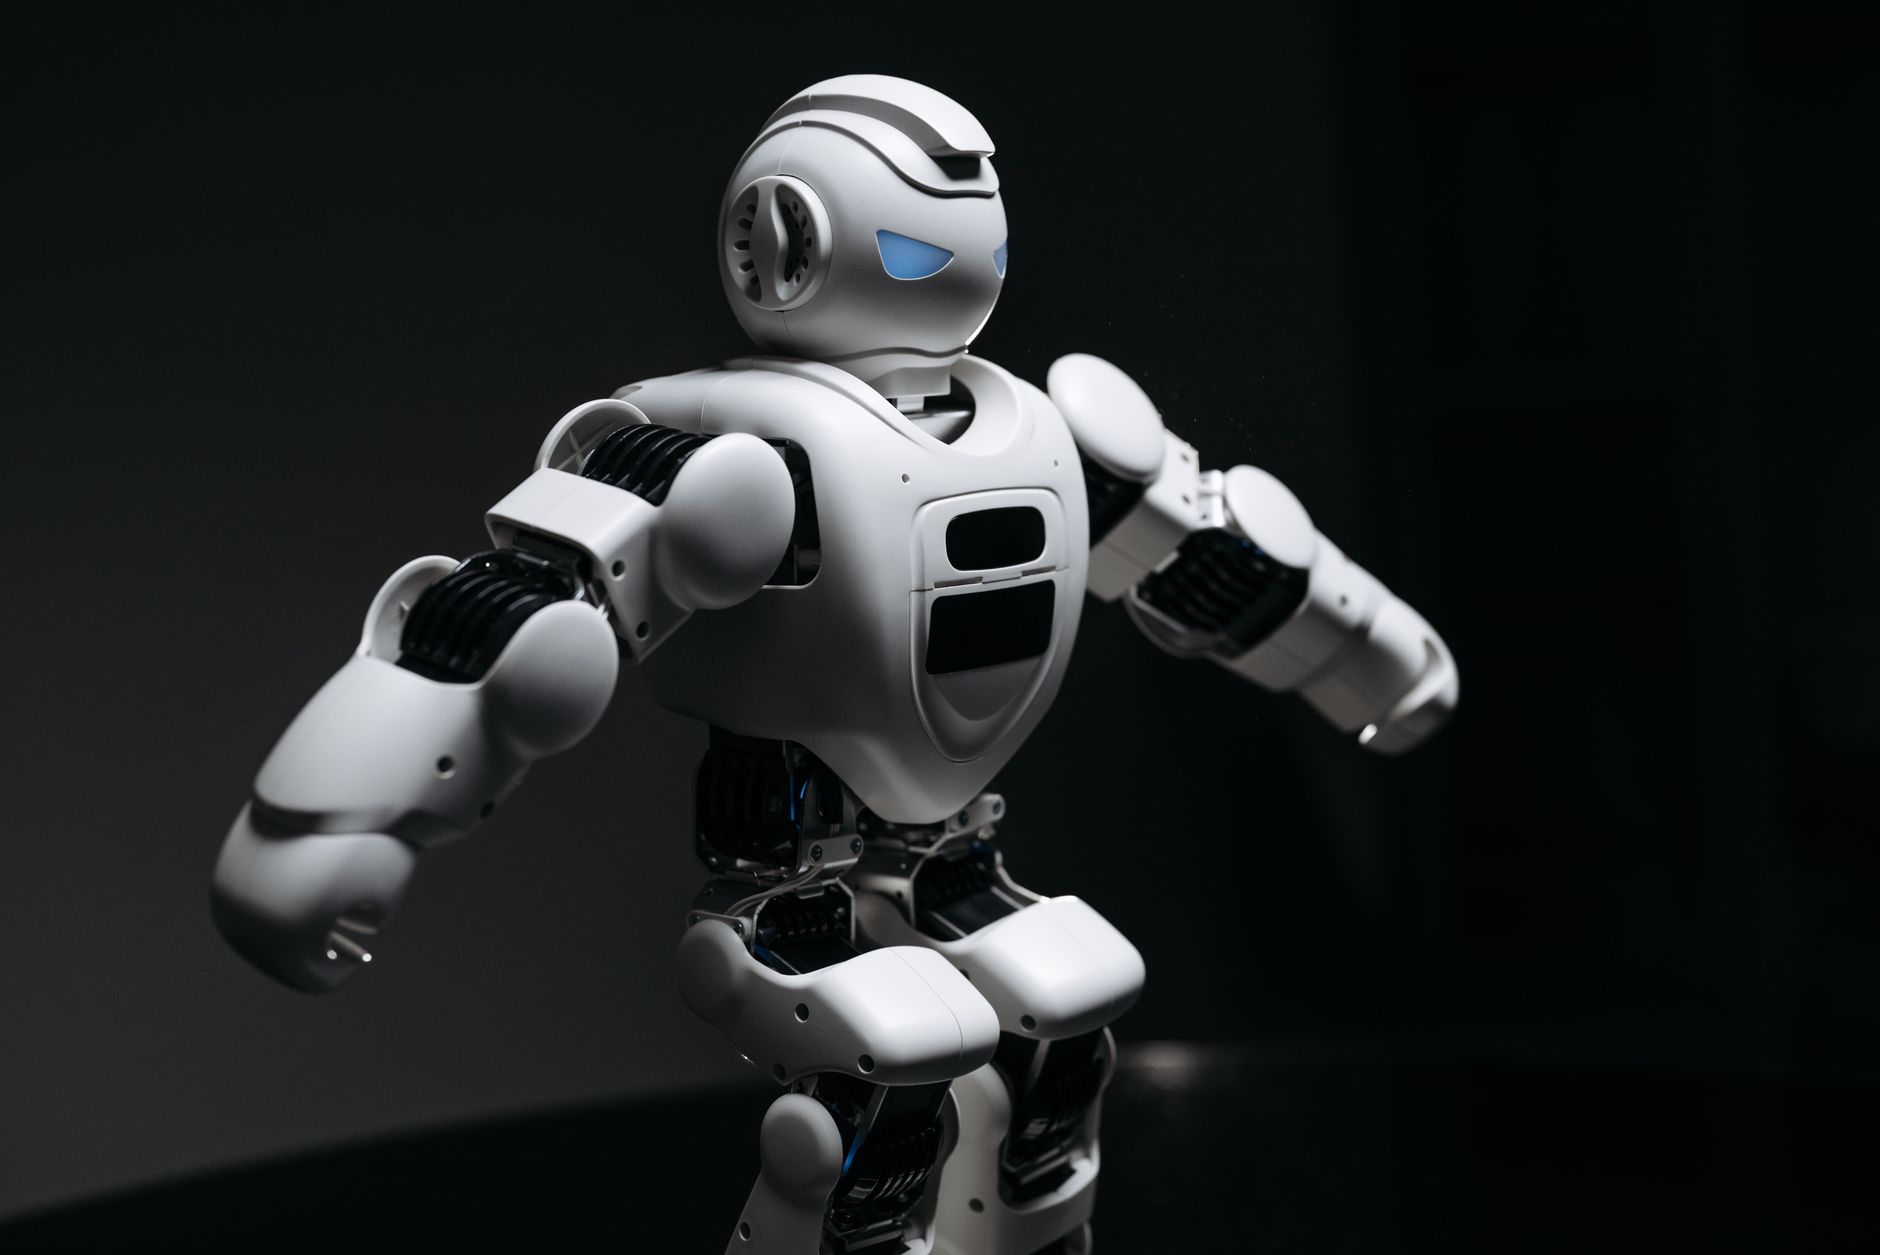
Foreign competition nonetheless looms. Tesla’s Optimus programme remains the most closely watched rival effort globally, and the rollout of autonomous vehicle platforms — as seen in recent developments around Tesla’s Cybercab — demonstrates how quickly American firms can transition from concept to commercial deployment when regulatory conditions allow. Chinese manufacturers will need to demonstrate not only production scale but also the software sophistication necessary to make general-purpose humanoids viable outside highly controlled factory settings, a challenge that remains unresolved industry-wide.
For investors, the pivot introduces a new valuation lens for Chinese EV stocks, which have largely traded on car delivery volumes and gross margin trajectories. If humanoid robot programmes mature into meaningful revenue contributors by 2028 or 2029, as some sell-side projections suggest, the earnings profiles of companies like Xpeng and BYD could look materially different from what current consensus models imply. The near-term risk, however, is that capital allocated to robotics delays the profitability recovery that shareholders had been anticipating from the automotive core — a tension that management teams will need to navigate carefully in the quarters ahead.