Sempra (NYSE: SRE) has secured a long-term liquefied natural gas supply agreement spanning two decades, a development that materially strengthens the commercial foundation of its Port Arthur LNG project and reduces the volume of uncontracted capacity that has weighed on investor sentiment. The deal, Yahoo Finance energy reported, is the latest in a series of offtake arrangements the San Diego-based energy infrastructure company has pursued as it races to secure final investment decisions on its flagship Gulf Coast export terminal.
The agreement is significant in the context of a broader reshaping of global energy trade flows. As European buyers continue diversifying away from Russian pipeline gas and Asian demand for LNG climbs, long-term supply contracts have become the currency of credibility for project developers seeking lender confidence and equity backing. Sempra’s move mirrors a wider trend examined in discussions around Hormuz oil dynamics, where geopolitical disruption has accelerated the appetite among importers for locked-in, long-duration supply security.
What the 20-Year Term Means for Project Financing and Cash Flow Visibility
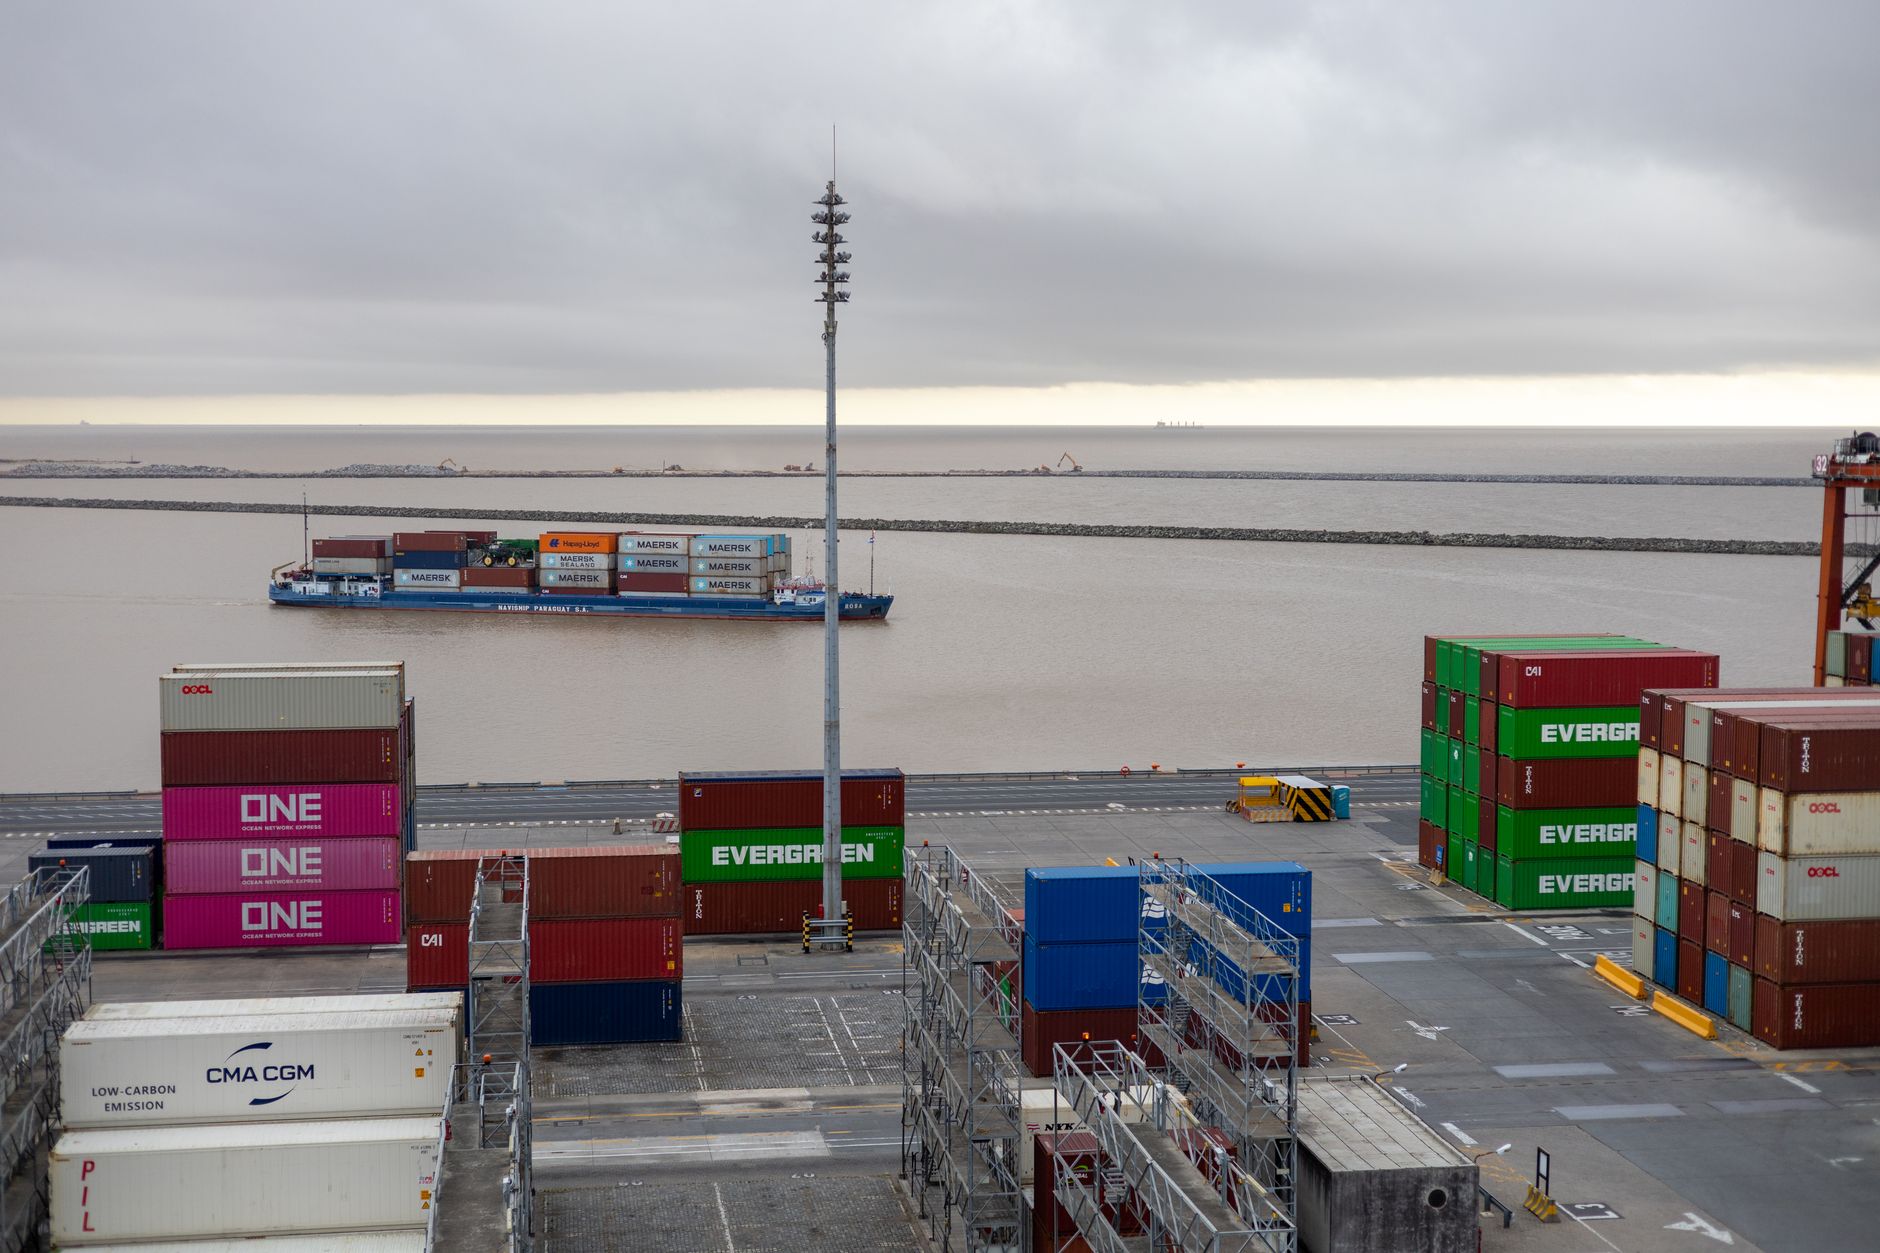
Long-term offtake agreements are the bedrock of project finance in the LNG sector. Lenders typically require a substantial portion of a facility’s nameplate capacity to be covered by creditworthy counterparties under fixed or floor-priced contracts before committing debt capital. The addition of a 20-year deal meaningfully raises the contracted percentage of Port Arthur LNG’s Phase 1 capacity, reducing the speculative, merchant-exposure element that carries higher perceived risk on lender and rating agency scorecards.
Port Arthur LNG Phase 1 is designed to produce approximately 13 million tonnes per annum of LNG. Each contracted tonne per annum represents a predictable revenue stream that backstops debt service coverage ratios. While Sempra has not disclosed the precise financial terms of the newest agreement, comparable deals in the market typically involve capacity fees in the range of $2.00 to $3.50 per million British thermal units, layered on top of commodity cost pass-throughs, effectively insulating the project developer from direct fuel price exposure. For equity investors, this structure converts what could be a volatile commodity play into something closer to a regulated utility revenue model, which is the profile Sempra’s management has consistently marketed to Wall Street.
Residual Risks That the Contract Alone Cannot Eliminate
Despite the commercial progress, a 20-year agreement does not render the project risk-free. Construction cost inflation remains a live concern across the entire U.S. LNG development pipeline. Large-scale liquefaction projects have historically run over budget and behind schedule, and the post-pandemic environment of elevated materials and labor costs has not fully normalized. Cost overruns can erode the economics of even a fully contracted book, squeezing equity returns without breaching the contractual framework that protects lenders.
Regulatory and policy risk also persists. The U.S. Department of Energy’s permitting environment for LNG exports has been subject to periodic review, and any future administration could impose additional scrutiny on new export authorizations or project modifications. Sempra must also navigate the capital allocation pressures inherent in running a diversified energy utility alongside a capital-intensive infrastructure development program. As corporate margin pressures continue to affect the broader U.S. industrial complex, the cost of financing a multi-billion-dollar construction program in a higher-for-longer interest rate environment represents a genuine drag on projected returns.
Furthermore, counterparty credit quality matters as much as contract duration. A 20-year agreement is only as robust as the financial standing of the buyer on the other side of it. If the contracting party is a sovereign utility or a highly rated energy major, the risk profile differs substantially from an agreement with a smaller or more leveraged trading house. Sempra has not publicly identified the counterparty, leaving analysts to estimate the credit quality implications from context clues in regulatory filings.
On balance, the agreement represents a meaningful de-risking milestone for Port Arthur LNG, moving Sempra closer to the contracted coverage thresholds that unlock large-scale project financing. But with construction yet to fully ramp, permitting contingencies still on the table, and global LNG demand projections carrying their own uncertainty horizon, the company’s execution over the next 24 to 36 months will determine whether this commercial momentum translates into delivered shareholder value.