For millions of international travelers, the assumption that a standard health insurance policy or travel credit card will cover a medical emergency overseas is a costly misconception. According to PRNewswire data, 62 percent of travelers are wrong about what their travel credit card actually covers, a gap in understanding that becomes financially devastating when a helicopter airlift or air ambulance is required. Emergency medical evacuation — the process of transporting a critically ill or injured traveler to the nearest adequate medical facility or back home — can easily exceed $100,000 out of pocket without dedicated coverage, and in remote or politically unstable regions, costs can climb far higher.
As international travel volumes continue to recover and expand — a trend reflected in carriers’ aggressive global route expansion, including Airlines’ international growth strategy for 2027 — demand for specialist travel insurance products has followed. Emergency medical evacuation insurance, sometimes bundled within comprehensive travel insurance plans, has moved from a niche product to a mainstream financial consideration for frequent travelers, expatriates, and adventure tourists alike.
What the Coverage Actually Includes
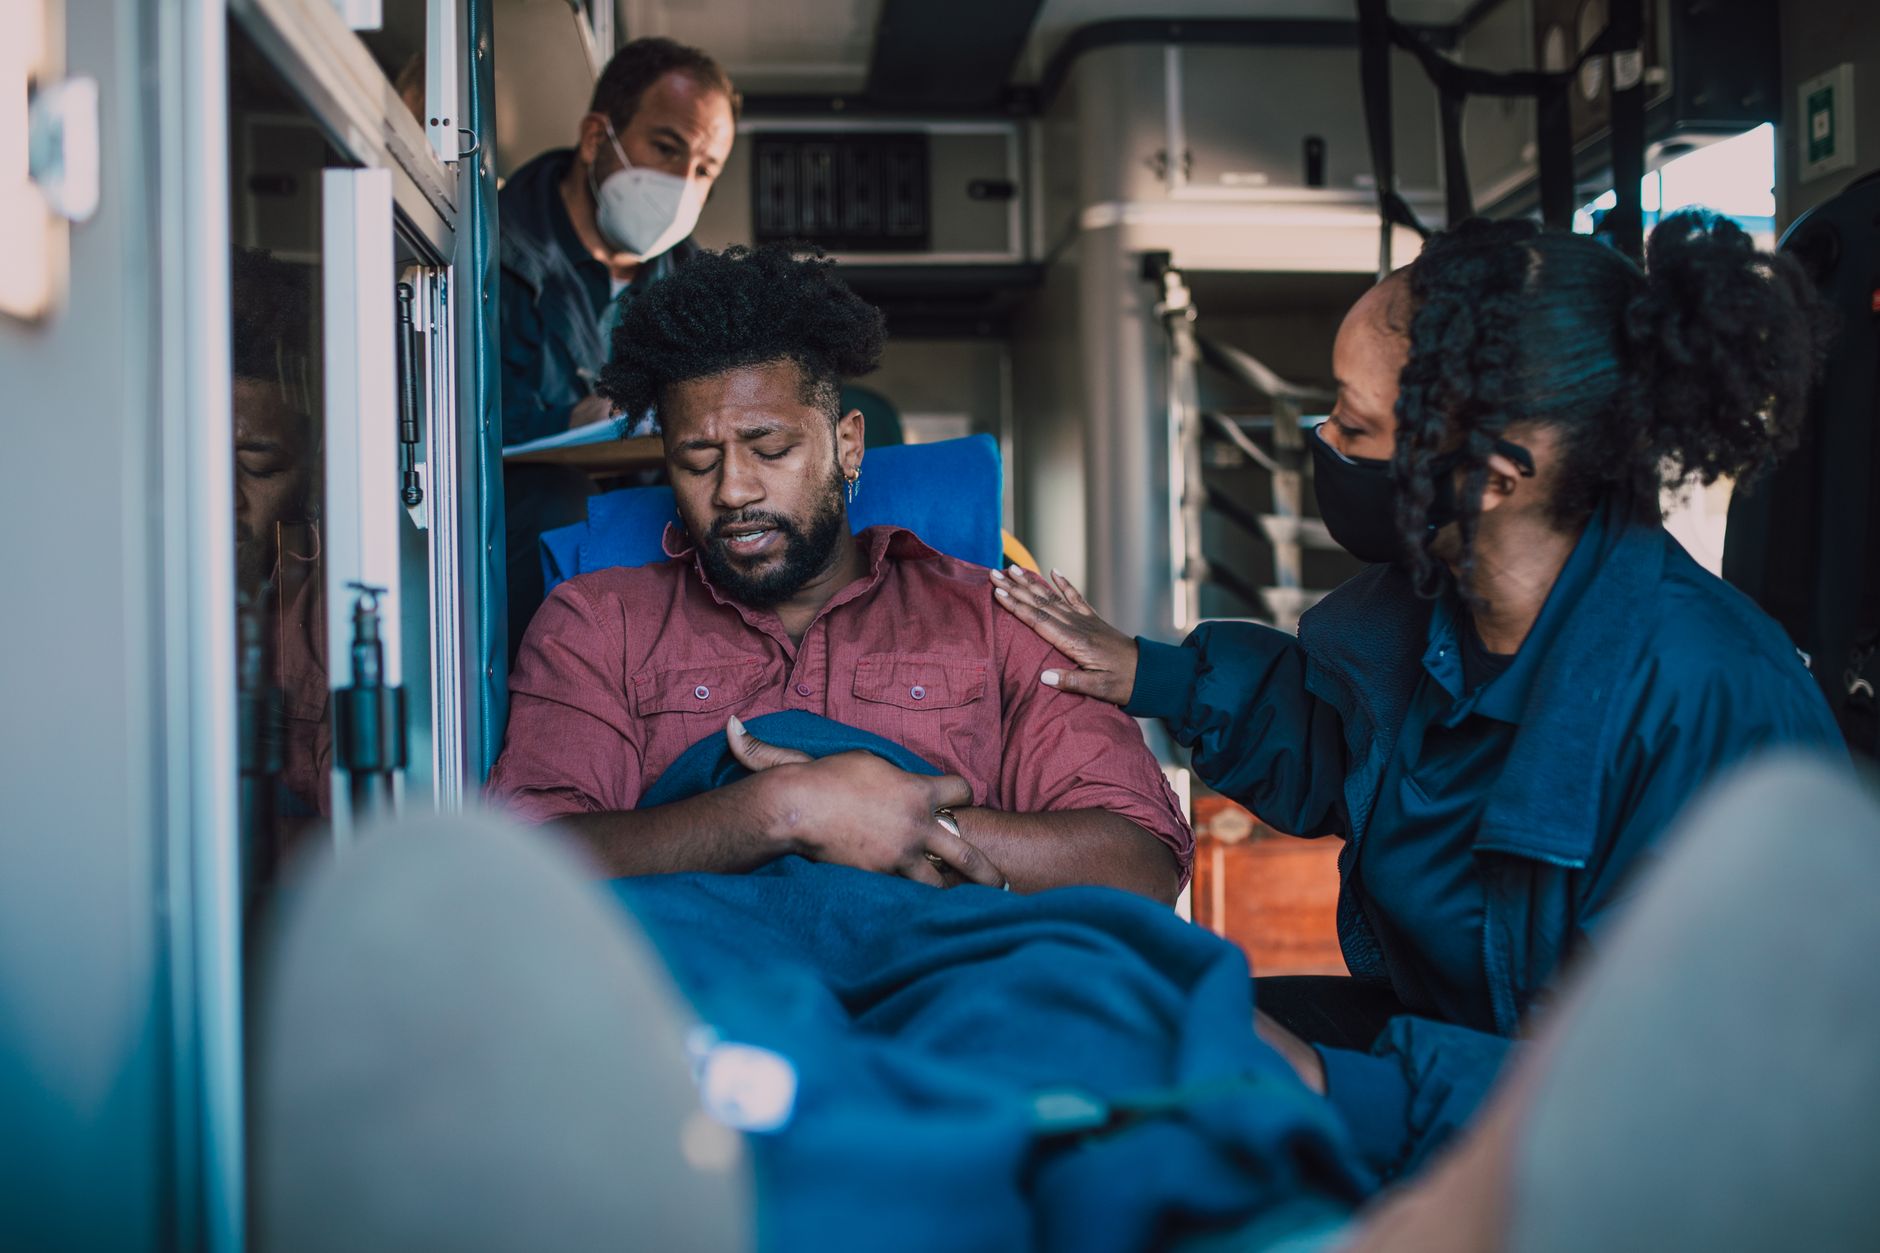
Emergency medical evacuation insurance is distinct from standard travel insurance. According to an analysis by Yahoo Finance, the coverage typically pays for transportation to the nearest appropriate medical facility when a traveler’s condition cannot be adequately treated locally. This may involve ground ambulances, helicopter rescues, or fixed-wing air ambulances staffed by medical professionals. Some policies also cover repatriation — the cost of flying a patient back to their home country once they are stabilized — which represents a separate and often equally expensive logistics challenge.
The coverage does not typically pay for medical treatment itself, which is why financial advisers consistently recommend pairing evacuation coverage with a robust international health or travel medical insurance plan. Key exclusions commonly include pre-existing conditions, injuries sustained during high-risk activities such as certain adventure sports unless specifically added as a rider, and evacuations deemed not medically necessary by the insurer’s on-call physicians. Destination also matters: policies may carry carve-outs for regions under active conflict or subject to government travel advisories at the time of purchase.
Costs, Plan Structures, and How to Compare Options
Premium ranges vary considerably based on age, trip duration, destination, and the scope of coverage selected. Standalone annual evacuation membership plans — offered by providers such as Global Rescue and Medjet — typically range from approximately $119 to $330 per year for an individual, covering unlimited evacuations globally. Broader comprehensive travel insurance policies that bundle evacuation coverage alongside trip cancellation, baggage loss, and medical expense benefits can range from roughly $50 for a short domestic trip to $500 or more annually for a frequent international traveler, depending on the insured’s age and the declared trip value.
When comparing plans, financial advisers and consumer advocates highlight several critical variables. The evacuation benefit limit — some policies cap payouts at $500,000 while others offer unlimited coverage — is among the most consequential. Equally important is whether the insurer controls transportation decisions directly through a 24-hour coordination center or merely reimburses costs after the fact, since the latter arrangement can leave travelers navigating complex logistics during a crisis. Travelers should also confirm whether coverage applies to political evacuations, not merely medical ones, as instability in a destination can require urgent departure independent of any health emergency. For those managing broader household financial exposures — particularly during periods of elevated US inflation that compress discretionary budgets — an annual membership plan often represents a more cost-efficient structure than per-trip policies for anyone taking three or more international trips per year.
The bottom line for prospective buyers is to read policy language with the same scrutiny applied to any significant financial contract. Insurers price these products based on actuarial risk, and the cheapest plan frequently reflects meaningful coverage gaps. For most international travelers, the asymmetry is clear: premiums measured in hundreds of dollars per year against potential out-of-pocket exposure that can reach six figures in a single event.