A fresh wave of analyst commentary is shaping sentiment across the financial services sector, as banks, insurers, and asset managers contend with evolving credit conditions, rate expectations, and capital allocation pressures. The observations, compiled in the WSJ Market Talk roundup published by The Wall Street Journal, highlight the breadth of forces weighing on an industry that remains acutely sensitive to macroeconomic shifts. For investors tracking global equity movements, the divergence in financial sector performance across regions is becoming increasingly difficult to ignore.
The commentary spans a range of subsectors, with particular attention paid to how major financial institutions are positioning themselves ahead of anticipated changes in monetary policy. Analysts note that while headline earnings figures at several large banks have remained resilient, underlying metrics — including net interest margins, loan loss provisioning, and fee income trends — are painting a more cautious picture of the operating environment heading into the second half of the year.
Credit Conditions and Net Interest Margin Pressures Mount
Net interest margins remain a central focus for analysts evaluating the near-term earnings trajectory of commercial banks. As central banks in major economies signal a more gradual path toward rate cuts than markets had initially anticipated, lenders face the dual challenge of managing higher funding costs while contending with softening loan demand in key segments including commercial real estate and consumer credit. Several institutions have reportedly increased their provisions for credit losses in anticipation of a modest rise in delinquencies through the remainder of 2024.
Insurance carriers are similarly navigating a complex pricing environment. Property and casualty underwriters have benefited from successive years of premium rate increases, but analysts caution that competitive dynamics are beginning to reassert themselves in certain lines of business, compressing margins that had expanded sharply following a period of elevated catastrophe losses. Life insurers, meanwhile, are watching closely as spread income on fixed-income portfolios remains elevated relative to historical norms, providing a degree of earnings support even as new business volumes face headwinds from demographic shifts and changing consumer savings behavior.
Asset Managers and Wealth Platforms Face Fee Compression
The asset management industry continues to absorb the structural pressure of ongoing fee compression, as passive investment vehicles capture an ever-larger share of net new flows at the expense of active strategies. Publicly listed asset managers have responded with cost discipline and, in several cases, strategic consolidation — a trend that analysts expect to accelerate should equity market volatility diminish the performance-driven arguments that active managers rely upon to justify higher fee schedules. Assets under management figures across the sector remain elevated in absolute terms, buoyed by sustained equity market levels, but revenue per dollar of AUM continues its multi-year decline.
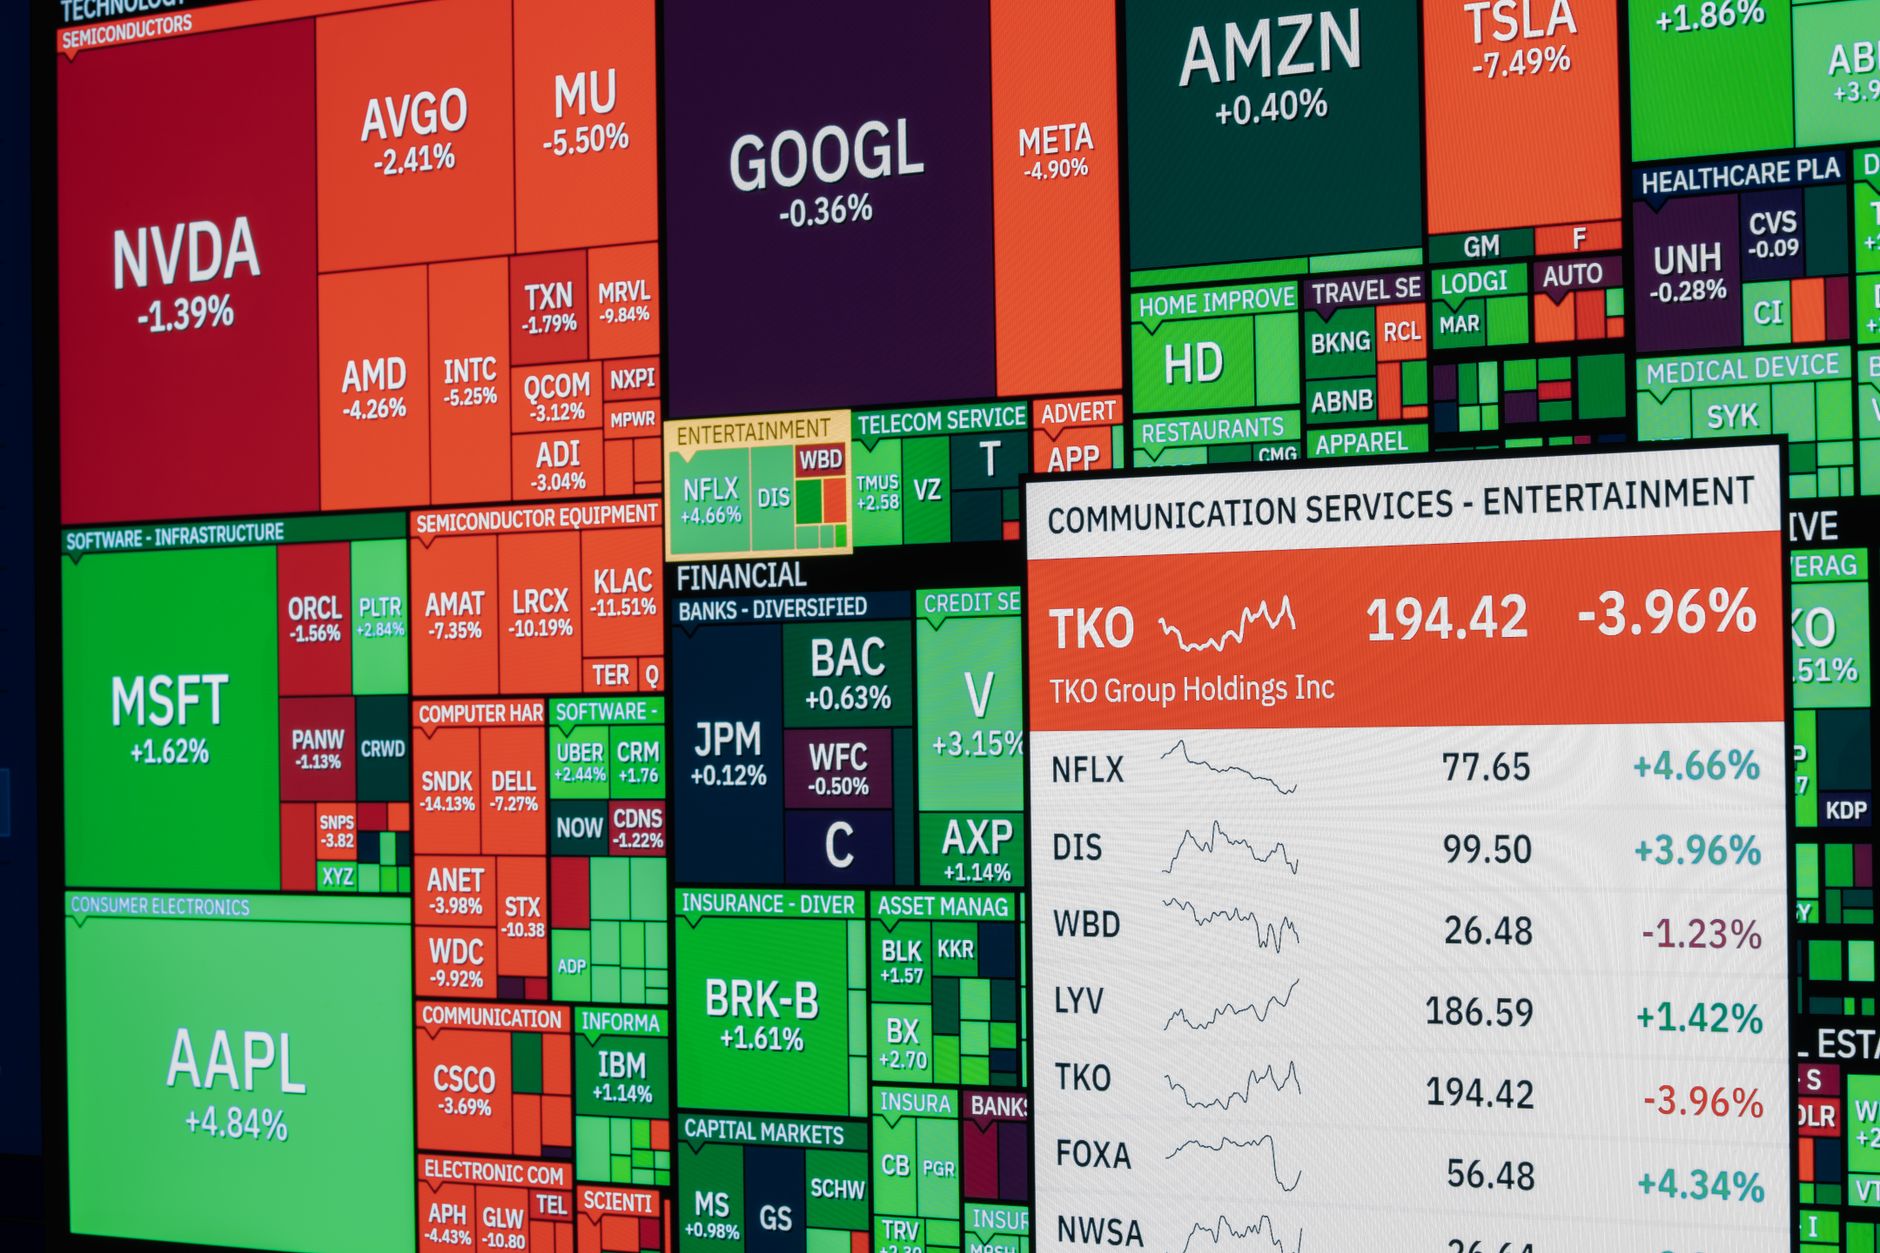
Wealth management platforms and brokerage operations are also drawing analyst scrutiny, particularly regarding their ability to monetize client assets in a rate environment that is gradually shifting. Margin lending balances and cash sweep revenues — which surged as interest rates rose from historic lows — are expected to face pressure as the rate cycle turns, prompting several firms to accelerate diversification into advisory fee income and alternative investment distribution. The competitive dynamics between traditional wirehouse models and independent registered investment advisor networks are also intensifying, with capital increasingly flowing toward platforms offering greater flexibility and lower cost structures.
Regulatory Overhang and Capital Planning Remain Key Watchpoints
Regulatory developments continue to cast a long shadow over financial services sector planning. The ongoing implementation of revised Basel III capital requirements — commonly referred to as the Basel endgame rules — remains a point of active negotiation between large institutions and their regulators, with final calibration of key ratios still subject to revision. Analysts note that even under more moderate scenarios than originally proposed, several systemically important banks may face constraints on capital return activity, including share buybacks, over the medium term.
Broader policy uncertainty is also a consideration. With debates over financial regulation intersecting with wider discussions about economic management — including concerns over inflation’s impact on household finances and consumer credit quality — the operating backdrop for financial services firms is unlikely to simplify materially in the near term. Analysts broadly advise investors to maintain selective exposure within the sector, favoring institutions with diversified revenue streams, strong capital buffers, and demonstrated ability to manage through credit cycle volatility.